Looking to Sell Your Property?
Begin your journey with a free property valuation. Get the facts and figures to make informed decisions.

Ask almost anyone on the high street whether first-time buyers can still afford to get onto the property ladder in Lincoln, and you will likely hear the same response: “Not these days.”
It is easy to see why that perception exists. With the typical entry-level home in Lincoln priced at £157,811, raising even a minimum 5% deposit (£7,890) while juggling rent and utility bills feels like an uphill struggle.
However, headline purchase prices tell only half the story. The decisive question for any prospective homeowner is far more practical: What percentage of monthly take-home pay actually goes toward servicing the mortgage?
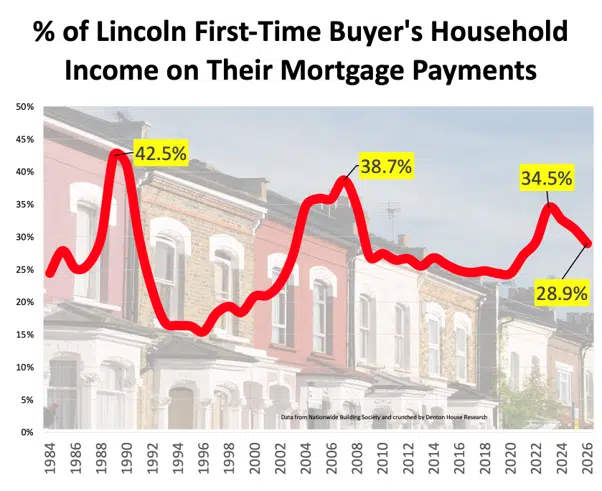
When evaluated through monthly mortgage servicing costs, Lincoln’s property market reveals a surprising historical perspective.
| Metric / Era | Average House Price | Mortgage Rate / Share of Income | National Average Comparison |
| 1989 Peak | £38,947 | 42.5% of income (at 14.5% interest) | 47.2% nationally |
| 2007 Pre-Crash | £120,000+ | 38.7% of income | 44.2% nationally |
| 2023 Rate Spike | £152,000+ | 34.5% of income | 37.4% nationally |
| 2026 (Current) | £157,811 | 28.9% of income | Substantially below historical peaks |
In 1989, a typical starter home in Lincoln cost just £38,947. In hindsight, it is easy to assume that homeownership back then was effortless.
The figures tell a different tale:
Committing over 40% of net income directly to mortgage debt left little safety margin for basic living expenses. A lower nominal purchase price did not translate to an easy monthly budget.
A similar squeeze unfolded in 2007, when Lincoln first-time buyers spent 38.7% of their monthly earnings servicing mortgage debt (against 44.2% nationally).
Key Takeaway: Prior generations paid lower purchase prices in cash terms, but often shouldered a significantly higher monthly burden relative to their earnings. Property prices and mortgage affordability are two distinct metrics.
Recent years have certainly brought their own pressures. Following rapid interest rate hikes, borrowing costs surged:
According to Nationwide regional data, Lincoln’s mortgage servicing burden has steadily eased:
Today, Lincoln first-time buyers spend 31.8% less of their household income on monthly mortgage payments than buyers in 1989, and 19.4% less than in 2007. While that does not make homeownership easy for everyone, it disproves the common belief that Lincoln homes are at an all-time low in affordability.
If monthly payments are comparatively lower today, why does buying still feel difficult?
The primary hurdle is the upfront cash deposit.
Even with monthly payments at 28.9% of household income, renters face major obstacles:
Because every household balance sheet is unique, raw percentages alone should not dictate when to buy. Interest rates, earnings, credit commitments, and mortgage term lengths all dictate what is sustainable for you.
If you plan to step onto the Lincoln property ladder over the coming years, avoid starting with maximum listing prices. Instead, work backwards from your monthly budget:
The typical entry-level home for a first-time buyer in Lincoln sits at approximately £157,811, requiring a minimum 5% deposit of roughly £7,890.
Lincoln first-time buyers commit around 28.9% of their household take-home pay to mortgage payments, down from 34.5% in 2023 and well below historical peaks of 42.5% in 1989.
Yes. Lincoln first-time buyers consistently spend a lower percentage of household income on mortgage payments than the national average (e.g., 28.9% locally vs historical national peaks exceeding 44%–47%).
While monthly mortgage servicing costs have moderated, accumulating the cash deposit alongside legal, survey, and moving fees remains the single largest financial bottleneck for local tenants.
Whether you are stepping onto the ladder or selling to upsize, market decisions should be guided by local facts rather than dramatic headlines.
If you are planning a move and would like an accurate, realistic assessment of your home’s current value, the team at Walters is here to help.
To maintain our high standards of direct, personalised customer service, we strictly limit our listings to 20 properties per month.
If you bought your first Lincoln home years ago, what proportion of your wage packet did that initial repayment take? If you are saving today, is the deposit or the mortgage your biggest obstacle? Share your experiences in the comments below!
Begin your journey with a free property valuation. Get the facts and figures to make informed decisions.
The reality of housing affordability in Newark may surprise you. Ask almost anyone on the high street whether first-time buyers can still
The Southwell residential property market has shifted over the past three years. Across the NG25 postcode sector, prospective buyers now ...
The Lincoln property market has experienced a distinct structural shift over the past three years. Across the LN1 to LN6 postcode districts,



"*" indicates required fields
"*" indicates required fields


