Looking to Sell Your Property?
Begin your journey with a free property valuation. Get the facts and figures to make informed decisions.

Ask almost anyone on the high street whether first-time buyers can still afford to get onto the property ladder in Newark and you will likely receive the same answer: “Not these days.”
It is easy to understand why. With the typical entry-level home in Newark priced at £171,378, saving even a minimum 5% deposit (£8,570) while managing rent and living expenses feels daunting.
However, purchase prices alone tell only half the story. The core question for any prospective buyer each month is practical: What proportion of household take-home pay does the mortgage actually take?
When viewed through monthly mortgage servicing costs, Newark’s property market reveals an encouraging historical perspective.
| Period / Benchmark | Average First Home Price | Mortgage Share of Household Income | National Average Comparison |
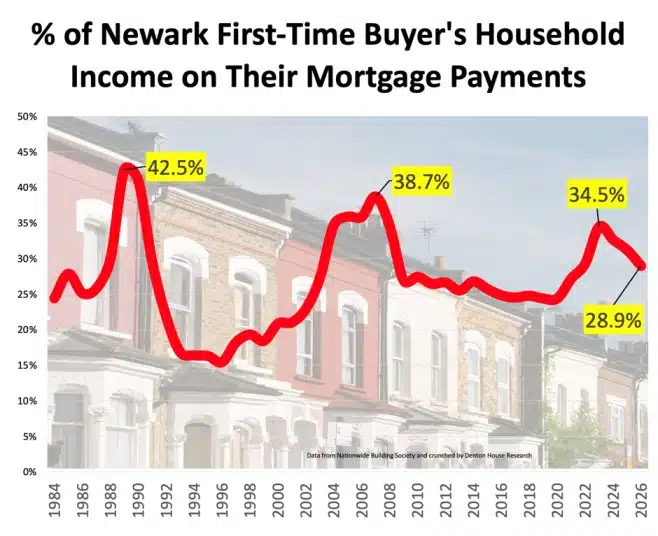
| 1989 Peak | £42,295 | 42.5% (at 14.5% interest) | 47.2% nationally |
| 2007 Peak | £130,000+ | 38.7% | 44.2% nationally |
| 2023 Spike | £165,000+ | 34.5% | 37.4% nationally |
| 2026 (Current) | £171,378 | 28.9% | Substantially below historical peaks |
In 1989, a typical starter home in Newark was priced at just £42,295. It is tempting to look at that figure and assume stepping onto the property ladder was straightforward.
The data shows a different picture:
Committing over 40% of net earnings directly to mortgage debt left little margin for everyday household bills. A lower nominal purchase price did not create an easy monthly budget.
A similar squeeze occurred in 2007, when Newark first-time buyers allocated 38.7% of their household income to mortgage repayments, against 44.2% across the UK.
Key Takeaway: Prior generations paid less in headline cash terms, but often committed a substantially larger portion of their monthly earnings to mortgage payments. Property prices and affordable monthly payments are two entirely different metrics.
Recent buyers have faced real headwinds as interest rates adjusted. When borrowing costs rose, the impact on monthly household cash flow was immediate:
According to Nationwide regional data, Newark’s mortgage servicing burden has steadily improved:
Today, Newark first-time buyers spend 31.8% less of their household income on mortgage payments than buyers in 1989, and 19.4% less than in 2007. While homeownership remains a major commitment, the claim that property in Newark is uniquely unaffordable today does not match the figures.
While monthly mortgage repayments are comparatively lower today, getting onto the ladder still poses challenges.
The biggest hurdle remains raising the upfront deposit.
Even with monthly payments at 28.9% of income, tenants face clear obstacles:
For this reason, top-line percentages alone should never dictate when to buy. Household income, existing debts, credit history, and personal commitments must determine your path.
If you plan to purchase your first home in Newark over the coming years, avoid starting with maximum property listings. Instead, work backwards from your monthly cash flow:
The typical entry-level home for a first-time buyer in Newark currently costs approximately £171,378, which requires a minimum 5% deposit of roughly £8,570.
In 2026, Newark first-time buyers spend an average of 28.9% of household take-home income on mortgage repayments, down from 34.5% in 2023 and well below historical peaks of 42.5% in 1989.
Yes. Newark buyers typically commit a lower percentage of household earnings to mortgage servicing (28.9%) compared to national figures, reflecting regional affordability advantages in Nottinghamshire.
While monthly mortgage serviceability has improved significantly since 2023, saving the cash deposit alongside legal, survey, and moving fees remains the primary barrier for renters.
Whether you are stepping onto the property ladder or planning to sell and upsize, property decisions should be guided by local market evidence rather than headlines.
If you are preparing for a move and want a clear assessment of your property’s current market value, the local team at Walters can help.
To ensure dedicated, high-touch customer service, we strictly limit our listings to 20 properties per month.
If you bought your first home in Newark years ago, what percentage of your salary went towards that first repayment? If you are saving today, is the deposit or the mortgage your biggest barrier? Share your thoughts below!
Begin your journey with a free property valuation. Get the facts and figures to make informed decisions.
By Walters Property Marketing | Lincoln Property Market Report: What’s Actually Selling in LN1–LN6 Quick Market Takeaway: In the Lincoln ...
When homeowners in Newark assess what their property is worth, attention naturally gravitates to location, square footage, kitchen update...
The reality of housing affordability in Lincoln may surprise you. Ask almost anyone on the high street whether first-time buyers can still



"*" indicates required fields
"*" indicates required fields


